Sales Tax Calculator
The Sales Tax Calculator determines any one of the following when the other two are provided: the pre-tax price, the sales tax rate, or the final (after-tax) price.
Sales Tax Rate: 0%
After Tax Price: $0.00
Related : Payment Calculator | Inflation Calculator
What is Sales Tax?
A sales tax is a type of consumption tax that is levied by a government on the sale of certain goods and services. This tax is generally collected by the seller or vendor at the point of purchase and then remitted to the government, effectively making the consumer responsible for paying it indirectly. The primary purpose of a sales tax is to generate revenue for public services, infrastructure, and governmental operations.
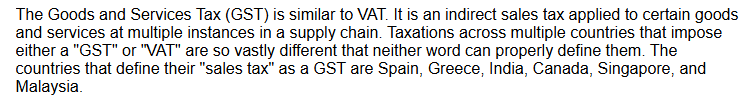
In many countries, what is commonly referred to as a sales tax takes the form of a value-added tax (VAT) or a goods and services tax (GST). While these taxes are technically distinct from a traditional sales tax, they operate on similar principles: they are levied on the consumption of goods and services, rather than on income or profits. VAT and GST systems often involve multiple stages of taxation throughout the production and distribution chain, with the final burden ultimately borne by the end consumer.
The way sales tax is displayed and applied can vary significantly between different countries and regions. In some places, the prices listed for products and services are exclusive of tax, meaning the applicable sales tax is added only at the time of purchase. In other locations, the prices shown to consumers already include the tax, reflecting the total amount the buyer will pay. This distinction can affect consumer perception, pricing strategies, and accounting practices for businesses.
Understanding sales tax is essential not only for consumers, who must be aware of the total cost of their purchases, but also for businesses, which are responsible for properly collecting, reporting, and remitting the tax to the appropriate government authority. Sales tax policies and rates vary widely around the world, influenced by local laws, economic conditions, and governmental priorities.
U.S. Sales Tax
In the United States, there is no federal sales tax, meaning that the federal government does not impose a tax on consumer purchases. Instead, sales tax is primarily administered at the state and local levels. Out of the 50 states, along with the District of Columbia, Puerto Rico, and Guam, only five states do not impose a statewide sales tax. These states are Alaska, Delaware, Montana, New Hampshire, and Oregon. In the remaining states, the sales tax rates vary significantly, and in addition to the state-level tax, many cities, counties, and other local jurisdictions are authorized to levy their own additional sales taxes, creating a complex patchwork of taxation across the country.
Unlike the value-added tax (VAT) commonly used in many other countries which is imposed at multiple stages of production and distribution sales tax in the U.S. is applied only to retail sales made directly to consumers. Most transactions between businesses, including wholesale purchases of goods or services, are generally exempt from sales tax. This means that the tax is primarily a consumption-based levy, paid by the end-user rather than intermediaries in the supply chain.
The actual rate of sales tax differs widely depending on the state, the local jurisdiction, and the type of good or service being purchased. Rates can range from as low as 0% in tax-free states to more than 16% in certain localities when state and local taxes are combined. Additionally, many states provide exemptions or reduced rates for specific types of products. For example, in Texas, prescription medicines and food seeds are exempt from taxation. In Vermont, while the general sales tax is 6%, an extra 10% tax is added to alcoholic beverages that are purchased for immediate consumption. These examples illustrate how tax rules can vary not only from state to state but also depending on the type of item being purchased.
The economic impact of sales tax on American households is significant. On average, sales taxes account for roughly 2 percent of an individual’s personal income, affecting the cost of everyday goods and services. Sales tax is a major source of revenue for state governments, contributing nearly one-third of their total revenues and ranking second only to income taxes in terms of importance. The reliance on sales tax, however, is not uniform across the country. States in the southern and western regions of the U.S. tend to depend more heavily on sales tax revenues, while New England states and the industrial Midwest rely on it to a lesser extent. For instance, Florida, Washington, Tennessee, and Texas generate more than 50 percent of their tax revenues from sales taxes, with some approaching 60 percent. In contrast, New York derives only about 20 percent of its state revenue from sales tax, relying more heavily on income and other taxes.
Overall, sales tax in the United States is a complex and highly localized form of taxation, with significant variation not only between states but also within individual jurisdictions. It plays a critical role in funding state and local government operations, influencing consumer behavior, and shaping economic policy across the country. Understanding the intricacies of sales tax is essential for consumers, businesses, and policymakers alike, given its broad impact on daily life and state finances.
The following is an overview of the sales tax rates for different states.
| State | General State Sales Tax | Max Tax Rate with Local/City Sales Tax |
|---|---|---|
| Alabama | 4% | 13.50% |
| Alaska | 0% | 7% |
| Arizona | 5.60% | 10.725% |
| Arkansas | 6.50% | 11.625% |
| California | 7.25% | 10.50% |
| Colorado | 2.90% | 10% |
| Connecticut | 6.35% | 6.35% |
| Delaware | 0% | 0% |
| District of Columbia | 6% | 6% |
| Florida | 6% | 7.50% |
| Georgia | 4% | 8% |
| Guam | 4% | 4% |
| Hawaii | 4.166% | 4.712% |
| Idaho | 6% | 8.50% |
| Illinois | 6.25% | 10.25% |
| Indiana | 7% | 7% |
| Iowa | 6% | 7% |
| Kansas | 6.50% | 11.60% |
| Kentucky | 6% | 6% |
| Louisiana | 4.45% | 11.45% |
| Maine | 5.50% | 5.50% |
| Maryland | 6% | 6% |
| Massachusetts | 6.25% | 6.25% |
| Michigan | 6% | 6% |
| Minnesota | 6.875% | 7.875% |
| Mississippi | 7% | 7.25% |
| Missouri | 4.225% | 10.85% |
| Montana | 0% | 0% |
| Nebraska | 5.50% | 7.50% |
| Nevada | 6.85% | 8.375% |
| New Hampshire | 0% | 0% |
| New Jersey | 6.625% | 12.625% |
| New Mexico | 5.125% | 8.688% |
| New York | 4% | 8.875% |
| North Carolina | 4.75% | 7.50% |
| North Dakota | 5% | 8% |
| Ohio | 5.75% | 8% |
| Oklahoma | 4.50% | 11% |
| Oregon | 0% | 0% |
| Pennsylvania | 6% | 8% |
| Puerto Rico | 10.50% | 11.50% |
| Rhode Island | 7% | 7% |
| South Carolina | 6% | 9% |
| South Dakota | 4% | 6% |
| Tennessee | 7% | 9.75% |
| Texas | 6.25% | 8.25% |
| Utah | 6.1% | 8.35% |
| Vermont | 6% | 7% |
| Virginia | 5.30% | 7% |
| Washington | 6.50% | 10.60% |
| West Virginia | 6% | 7% |
| Wisconsin | 5% | 7.9% |
| Wyoming | 4% | 6% |
U.S. History of Sales Tax
During the 18th century, when the United States was still a collection of British colonies, the English Crown imposed various taxes on the American colonists, including taxes on goods such as paper, glass, and tea. These taxes were levied without the consent or representation of the colonists in the British Parliament a situation famously summarized by the phrase “taxation without representation.” Among the many grievances this caused, one of the most iconic events was the Boston Tea Party of 1773, during which American colonists protested by dumping British tea into Boston Harbor. These tensions, combined with other acts of resistance and disputes over taxation and governance, ultimately contributed to the outbreak of the American Revolution. In a sense, the very foundation of the United States was shaped, at least in part, by conflicts surrounding the taxation of everyday goods.
After the Revolution, the concept of sales taxation in America became much more cautious and fragmented. There was never a federal sales tax imposed on the nation, largely because of the historical memory of colonial grievances and the desire to avoid repeating the mistakes of the past. Early experiments with sales taxes at the state level were often controversial and fraught with difficulties. Many of these early attempts faced challenges related to collection, enforcement, and fairness, which prevented widespread adoption for decades.
Sales tax only began to gain traction in the United States during the economic crisis of the Great Depression in the 1930s. At that time, state governments were struggling to raise sufficient revenue to fund essential public services, as traditional sources of funding, such as property taxes, were often insufficient or difficult to collect. Policymakers experimented with various methods to stabilize state finances, and sales tax emerged as an effective solution because it directly taxed the consumption of goods a form of economic activity that continued even during hard times. Mississippi became the first state to implement a modern state sales tax in 1930, and the idea quickly spread to other states, gradually becoming a standard component of state-level revenue systems.
Today, sales tax is imposed in most U.S. states and serves as a critical source of funding for state and local governments. While rates and rules vary widely between jurisdictions, the underlying principle remains the same: a tax on the sale of goods and, in some cases, services. Over the decades, sales tax has proven to be a generally effective way for states to generate revenue, supporting public infrastructure, education, health services, and other governmental functions. Its evolution from a colonial grievance to a fundamental fiscal tool highlights the unique history of taxation in the United States and explains why, unlike many other countries, the U.S. has relied primarily on state-level rather than federal consumption taxes.
How to Deduct Sales Tax in the U.S.?
When filing a federal income tax return in the United States, taxpayers must first decide whether to claim the standard deduction or to itemize their deductions. This choice depends on each individual’s financial situation, income level, and eligible expenses. For the majority of Americans, the standard deduction is the preferred option because it is simple to claim and often results in a comparable or larger reduction in taxable income without the need for detailed documentation.
Sales tax can only be deducted from federal income tax if a taxpayer chooses to itemize deductions. For individuals whose only potential deductible expense is sales tax, itemizing may not be worthwhile, as the effort involved often outweighs the financial benefit. Itemizing deductions requires careful and accurate record-keeping, since the Internal Revenue Service (IRS) may require proof of expenses. This typically means retaining receipts or other documentation for sales tax paid throughout the year, which can be time-consuming and tedious. Taxpayers who intend to itemize should consistently track and organize their expenses to ensure they can accurately calculate and support the amount of sales tax paid.
Once a taxpayer has decided to itemize deductions, an additional choice must be made: whether to deduct state and local income taxes or state and local sales taxes. Taxpayers are not allowed to claim both deductions and must select the one that provides the greater benefit. In most cases, deducting state and local income taxes results in a higher deduction, which is why it is the more commonly chosen option. However, there are certain situations in which deducting sales tax may be more advantageous.
Taxpayers who made significant purchases during the year such as buying a new car, paying for a wedding or engagement ring, taking an expensive vacation, or purchasing several major household appliances may find that their total sales tax payments exceed their state income tax payments. In these circumstances, claiming the sales tax deduction could lead to a greater reduction in taxable income. Despite this possibility, the sales tax deduction is relatively uncommon; in practice, fewer than 2 percent of Americans choose to deduct sales tax each year.
Understanding these options is important for making informed tax decisions and maximizing potential deductions. Tax laws and personal financial situations can vary widely, so taxpayers may benefit from carefully evaluating their expenses or consulting a tax professional. For additional details or to perform calculations related to income taxes, you may find it helpful to visit an Income Tax Calculator, which can provide further guidance and personalized estimates.
Value-Added Tax (VAT)
Value-added tax (VAT) is a form of consumption tax that is widely used outside of the United States and has been adopted by more than 160 countries around the world. Unlike the traditional U.S. sales tax, which is generally applied only at the final point of sale to the end consumer, VAT is an indirect tax that is collected at multiple stages throughout the production and distribution process. Each time value is added to a product or service whether through manufacturing, transportation, wholesale, or retail a portion of VAT is assessed.
Countries that implement VAT systems often apply the tax not only to domestically produced goods and services but also to imports and exports, ensuring a consistent tax framework for both local and international trade. Under a VAT system, all participants in the supply chain including suppliers, manufacturers, wholesalers, distributors, and retailers are typically responsible for collecting and remitting VAT. Although the tax is paid at each stage, businesses can usually claim credits for VAT already paid on inputs, meaning the ultimate tax burden still falls on the final consumer. VAT is commonly calculated as the difference between the sales price of a good or service and the cost of materials or components that have already been taxed earlier in the supply chain.
A 1979 study published by the Tax Foundation provided valuable insight into the advantages and disadvantages of VAT when compared to traditional sales tax systems. One of the most significant benefits of VAT is its resistance to tax evasion. Because tax is applied at every step of production, businesses have a strong incentive to maintain accurate records and report transactions properly, making it much harder to evade taxes entirely. Additionally, VAT encourages better cost control and efficiency, as each participant in the supply chain is directly accountable for the tax on the value they add. Compared to a single-stage sales tax, VAT is also capable of generating more government revenue at the same tax rate due to its broader and more consistent tax base.
However, VAT is not without its drawbacks. It is often considered a regressive tax, meaning it places a proportionally greater burden on lower-income individuals, who tend to spend a higher percentage of their income on consumption. Critics also argue that the cumulative nature of VAT can disadvantage new or marginal businesses that lack the financial flexibility to manage upfront tax payments. Furthermore, VAT systems may contribute to inflationary pressures by increasing the overall cost of goods and services. There are also concerns that VAT can negatively affect exports if not properly structured, as higher production costs may reduce international competitiveness.
Despite these criticisms, VAT remains one of the most widely used forms of consumption taxation worldwide due to its efficiency and revenue-generating potential. Understanding how VAT works is essential for businesses engaged in international trade and for consumers in VAT-based economies. For more detailed information or to perform calculations related to VAT, you may find it useful to visit a VAT Calculator, which can help estimate tax amounts and clarify how VAT applies in different situations.
Goods and Services Tax (GST)
Frequently Asked Questions
What is a Sales Tax Calculator?
A Sales Tax Calculator is an online tool that helps users quickly calculate the sales tax applied to a product or service. By entering the original price and the applicable sales tax rate, the calculator determines the tax amount and the final price after tax. It eliminates manual calculations and ensures accuracy, making it useful for shoppers, businesses, and accountants.
How to use this Sales Tax Calculator?
To use a Sales Tax Calculator, enter at least two of the following values: the before-tax price, the sales tax rate, or the after-tax price. Once the required values are entered, click the Calculate button. The calculator will automatically compute the missing value and display the tax amount and total price. You can also use the Clear button to reset all fields and start a new calculation.
What’s the difference between sales tax and excise tax?
Sales tax is a general consumption tax applied to the sale of most goods and services and is usually calculated as a percentage of the purchase price. Excise tax, on the other hand, is a specific tax imposed on particular products such as gasoline, alcohol, tobacco, or luxury items. While sales tax is paid by consumers at checkout, excise tax is often included in the product’s price and may be paid by manufacturers or distributors.
What is the best definition of sales tax?
Sales tax is a government-imposed tax on the sale of goods and services, collected by sellers at the point of purchase and paid by consumers. The revenue generated from sales tax is commonly used to fund public services such as education, transportation, and public safety.
What is the concept of sales tax?
The concept of sales tax is based on taxing consumption rather than income or wealth. It ensures that individuals contribute to government revenue when they spend money on goods or services. Sales tax rates and rules vary by jurisdiction, and in many regions, both state and local governments may impose sales taxes.
What is the formula to calculate sales tax?
The basic formula to calculate sales tax is:
Sales Tax = Purchase Price × (Sales Tax Rate ÷ 100)
To find the total price after tax:
Total Price = Purchase Price + Sales Tax
How to calculate tax amount?
To calculate the tax amount, multiply the original price of the item by the sales tax rate expressed as a decimal. For example, if an item costs $100 and the sales tax rate is 8%, the tax amount would be $8. Adding the tax to the original price gives a final cost of $108. A Sales Tax Calculator simplifies this process and reduces the chance of errors.