Interest Calculator
This Compound Interest Calculator helps you calculate the growth of your investments, including both fixed principal amounts and regular additional contributions. You can also factor in optional considerations, such as taxes on interest income and inflation.
Interest Calculator
Total Principal: $0.00
Total Contributions: $0.00
Total Interest: $0.00
Interest of Initial Investment: $0.00
Interest of Contributions: $0.00
Buying Power After Inflation: $0.00
Schedule
| Period | Deposit | Interest | Ending Balance |
|---|
Growth Chart
Related | Mortgage Calculator | Loan Calculator | Auto Loan Calculator
Interest is the payment a borrower makes to a lender for the use of money, expressed either as a percentage or a specific amount. It serves as the foundation for most financial instruments worldwide.
Interest can be calculated in two main ways: simple interest and compound interest.
Simple Interest
Let’s look at a basic example of interest. Derek wants to borrow $100 (the principal) from the bank for one year, and the bank charges 10% interest. To calculate the interest:
Adding this interest to the principal gives Derek’s total repayment after one year:
So, Derek owes the bank $110: $100 for the principal and $10 as interest.
If Derek borrowed $100 for two years with annual simple interest, the bank charges interest each year separately:
After two years, Derek owes $120: $100 principal and $20 interest.
The formula for simple interest is:
If interest is applied more frequently, such as monthly or daily, the formula becomes:
However, simple interest is rarely used in practice. Most of the time, when people talk about “interest,” they mean compound interest.
Compound Interest
Compound interest requires more than one period. Returning to Derek’s example: he borrows $100 for two years at 10% interest. In the first year, interest is calculated as usual:
Adding this to the principal gives:
For the second year, interest is calculated on the new total ($110), not just the original principal:
Adding this interest gives Derek’s total repayment:
With compound interest, Derek owes $121 instead of $120 with simple interest. This happens because interest is earned on interest.
The more frequently interest is compounded within a period, the higher the total interest earned. For example, a $1,000 investment at 20% interest grows faster with more frequent compounding.
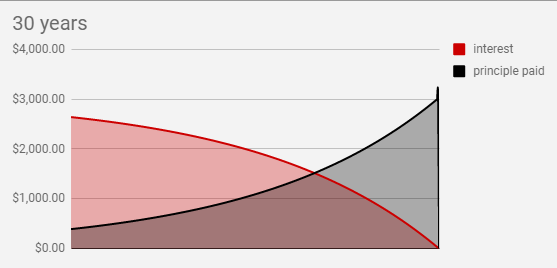
At the beginning, there is minimal difference between the various compounding frequencies, but as time progresses, they gradually begin to diverge. This clearly demonstrates the well-known power of compound interest in a simple visual form. Continuous compounding consistently produces the highest return because it represents the mathematical limit of how frequently interest can be compounded within a given time period.
The Rule of 72
The Rule of 72 is a handy mental shortcut for anyone looking to quickly estimate compound interest. While it doesn’t provide the precise results of a financial calculator, it is useful for approximating values. The rule states that to estimate the number of years required to double an investment, you simply divide 72 by the annual interest rate.
Example: How long will it take to double $1,000 at an interest rate of 8%?
At an 8% interest rate, it will take approximately 9 years for $1,000 to grow to $2,000. The Rule of 72 is most accurate for interest rates between 6% and 10%, but it remains a reasonable estimate for rates up to 20%.
Fixed vs. Floating Interest Rate
The interest rate on a loan or savings account can be either fixed or floating. Floating rates are typically tied to a benchmark or reference rate, such as the U.S. Federal Reserve (Fed) funds rate or the London Interbank Offered Rate (LIBOR). In most cases, loan rates are set slightly above the reference rate, while savings rates are set slightly below it, with the difference representing the bank’s profit.
Both the Fed rate and LIBOR are short-term interbank interest rates. The Fed rate is the primary tool used by the Federal Reserve to manage the money supply in the U.S. economy, while LIBOR reflects the average interest rates at which highly creditworthy institutions lend to one another. This Interest Calculator, however, is designed to work exclusively with fixed interest rates.
Contributions
The Interest Calculator above supports periodic deposits or contributions, making it ideal for users who regularly save a fixed amount. An important factor to consider is whether these contributions are made at the beginning or the end of each compounding period. Contributions made at the end of a period earn interest for one fewer compounding cycle compared to those made at the beginning.
Tax Rate
Certain types of interest income are subject to taxation, including earnings from bonds, savings accounts, and certificates of deposit (CDs). In the United States, interest earned from corporate bonds is almost always taxable. Some forms of interest income are fully taxed, while others receive partial tax advantages. For instance, interest earned on U.S. Treasury bonds is typically subject to federal income tax but is generally exempt from state and local taxes. These differences in tax treatment can significantly affect the overall return on an investment.
Taxes can have a substantial impact on the final balance of savings or investments, especially over long periods where compound interest is involved. Even a modest tax rate can greatly reduce the benefits of compounding over time. For example, if Derek invests $100 at an annual interest rate of 6% for 20 years in a tax-free environment, his investment would grow as follows:
However, if Derek’s interest earnings are taxed and he is in a marginal tax bracket of 25%, the outcome changes dramatically. Because the tax applies to the interest earned during each compounding period, the effective growth rate is reduced. As a result, instead of ending with $320.71, Derek would have only $239.78 after taxes.
This example highlights how taxes can erode the power of compound interest and why it is important for investors and savers to consider tax implications when choosing financial products. Selecting tax-advantaged accounts or investments can help preserve returns and maximize long-term growth.
Inflation Rate
Inflation refers to the long-term and sustained increase in the prices of goods and services across an economy. As inflation rises over time, the purchasing power of money declines, meaning that the same fixed amount of money will be able to buy fewer goods and services in the future than it can today. In the United States, the average inflation rate over the past century has been approximately 3% per year, making inflation a critical factor to consider when evaluating savings and investment growth.
For comparison, the average annual return of the S&P 500 (Standard & Poor’s) index during the same time period has been around 10%. This contrast highlights why investing, rather than simply saving cash, is often necessary to outpace inflation and grow wealth over the long term. To better understand how inflation affects purchasing power and financial planning, users can explore more detailed insights using our Inflation Calculator.
When using the Interest Calculator, setting the inflation rate to 0% can be helpful for obtaining quick, generalized results. However, for more realistic and accurate projections, entering an estimated inflation rate allows the calculator to adjust returns accordingly. This provides a clearer picture of how much an investment or savings balance will truly be worth in real terms, after accounting for rising prices.
The combined effects of taxation and inflation make it especially challenging to grow the real value of money. For example, in the United States, middle-income earners often face a marginal tax rate of around 25%, while inflation averages about 3% annually. Under these conditions, an individual must earn a stable interest or investment return of at least 4% simply to preserve their purchasing power. Achieving returns above this threshold is not always easy, underscoring the importance of thoughtful financial planning, smart investment choices, and awareness of both inflation and tax impacts on long-term financial goals.
Frequently Asked Questions.
1 : What do you mean by interest?
Interest is the additional money paid or earned on a principal amount over a period of time. When you borrow money from a bank or financial institution, interest is the cost you pay for using that money. Conversely, when you deposit money in a savings account or invest in financial products, interest is the reward you earn for allowing the bank or institution to use your funds. Interest is usually expressed as a percentage of the principal amount and can be calculated in different ways, such as simple interest or compound interest, depending on the terms of the loan or investment.
2 : What is 5% interest on $5,000?
A 5% interest on $5,000 represents the amount of money earned or paid in addition to the principal over a specific period, usually one year. To calculate it, multiply the principal ($5,000) by the interest rate (5%), which equals $250. This means if you invest $5,000 at a 5% annual interest rate, you will earn $250 in one year. If the interest is compounded, the total earnings could be slightly higher depending on the frequency of compounding.
3 : What is the 7% interest for 1 lakh?
For a principal of 1 lakh (100,000) at a 7% annual interest rate, the interest earned or payable over one year is 7,000. This is calculated by multiplying 100,000 × 7% = 7,000. If the interest is simple, this remains the total additional amount for the year. However, if the interest is compounded, the total interest earned will grow faster because the interest itself earns interest in each compounding period. Understanding this difference helps in planning savings and investments more effectively.
4 : What is interest in math?
In mathematics, interest is the additional amount calculated on a principal sum over a period of time, typically expressed as a percentage. Math uses formulas to determine interest, which can be simple or compound. Simple interest is calculated only on the original principal, while compound interest is calculated on the principal plus any interest that has already been earned. Interest calculations are widely used in finance, banking, and economics to project earnings, loan payments, and growth of investments over time.
5 : What is an interest calculator?
An interest calculator is an online or software tool designed to compute the interest earned or payable on loans, deposits, or investments. By entering details such as principal amount, interest rate, time period, and compounding frequency, users can quickly determine how much their money will grow or what they owe. Interest calculators are useful for budgeting, financial planning, and comparing different savings or loan options, helping individuals make informed financial decisions without manually performing complex calculations.